Card payments are ordinary now. The Federal Reserve’s 2026 Diary of Consumer Payment Choice puts the average American at 47 payments a month: 16 by credit card, 15 by debit, and 6 in cash. Accepting those cards is not free, and the advertised rate is rarely the full bill.
The best digital payment services for small businesses are the ones that match how you sell, not the ones with the lowest headline percentage. This comparison covers Square, Stripe, PayPal, Helcim, and Chase Payment Solutions on US list rates reported in 2026. Processors change fees often. Check the company page before you sign, and treat this as education rather than advice.
How to compare payment services
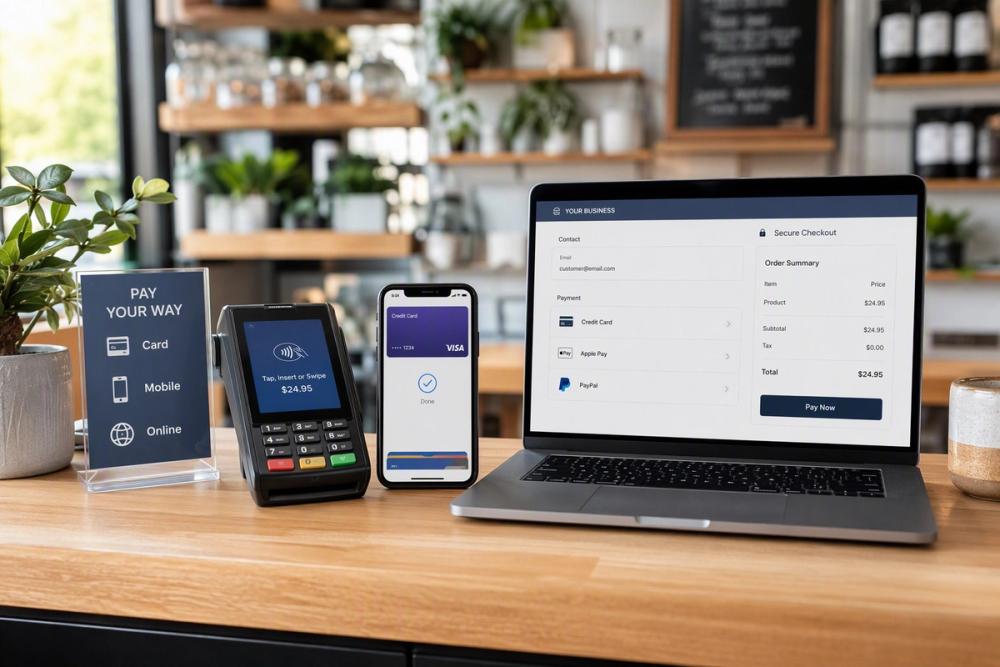
Start with the channel. A cafe, an online shop, and a freelancer who invoices have different costs even when they use the same brand.
Then look at the pricing model. A flat rate is a percentage plus a fixed fee on every sale. You can predict it. Interchange-plus passes through the card network’s interchange and adds a markup. It is harder to read on a statement. Past roughly $8,000 to $10,000 a month in card sales, it often costs less than a flat rate, according to a July 2026 processor comparison.
The number that matters is your effective rate. Divide total processing fees by card sales for a full month. A 2.6% sign on the website can land closer to 3% once fixed fees, keyed cards, and monthly add-ons are in.
Also check keyed-entry surcharges, dispute fees, PCI charges, hardware that works with only one processor, and contract length. Same-day deposit is useful. At many fintechs it costs about 1.5% to 1.95%. A bank that deposits the same day at no extra cost can be the cheaper version of speed.
Square, for a shop that also sells online
Square fits retailers, cafes, and service businesses that want a free point-of-sale app and simple card readers. Inventory tools come with it, which matters if you sell the same stock in person and online.
On the Free plan, in-person cards are 2.6% + 15¢. Online and invoice cards are 3.3% + 30¢. Manually keyed cards are 3.5% + 15¢. Those figures match Square’s published US pricing as checked by NerdWallet and other 2026 fee roundups. The in-person fixed fee used to be 10¢, and the free online rate used to be 2.9% + 30¢. Small tickets feel the new fixed fee. A $40 tap costs $1.19. The same $40 sale taken online costs $1.62.
Paid plans lower the rates and add a monthly fee. Run last month’s volume through both before you assume Free is cheaper.
Stripe, for a business that starts on the web
Stripe is the default when the sale happens on a website. Hosted checkout does not require you to build a payments stack. Subscriptions, invoices, and extra payment methods are there if the business grows into them.
US list rates in the July 2026 snapshot are 2.9% + 30¢ online and 2.7% + 5¢ in person, with no monthly fee. Confirm them on Stripe’s pricing page. The in-person fixed fee is lower than Square’s, so cheap counter sales can cost less here. Online, Stripe’s 2.9% + 30¢ beats Square Free’s 3.3% + 30¢.
The tradeoff is fit. A solo owner can take a first payment without a developer. The deeper tools assume someone is comfortable with settings, webhooks, and test modes.
PayPal, when customers already have a wallet
PayPal is often an acceptance layer rather than the only processor. Shoppers who want to pay from a PayPal or Venmo balance will leave if the button is missing. Invoicing works for anyone with an email address.
Rates read from PayPal’s business fees page in that July 2026 roundup: PayPal checkout at 3.49% + 49¢, standard online card processing at 2.99% + 49¢, and in-person payments through Zettle at 2.29% + 9¢. Invoice ACH is 1%, capped at $10. That cap is why a large invoice paid from a bank account can be far cheaper than the same invoice paid by card.
The 49¢ fixed fee is the problem on small online orders. A $40 card payment at 2.99% + 49¢ costs about $1.69, more than Stripe on the same sale. On a $400 invoice the percentage matters more and the fixed fee fades.
Helcim, when volume makes the flat rate hurt
Helcim uses interchange-plus and does not charge a monthly fee. The July 2026 list markup is about interchange + 0.40% + 8¢ in person and interchange + 0.50% + 25¢ online. Rates step down as volume rises. Service firms and wholesalers with steady card sales are the usual fit. Check Helcim’s pricing page because interchange itself moves.
Public review counts are still thin, so a star rating would be noise. The product set is also smaller than Square’s or Stripe’s. If you need a kitchen display or a large app store, this is the wrong shortcut.
Chase, if the business account is already there
Chase Payment Solutions is the bank option. Snapshot flat rates are 2.6% + 10¢ in person and 2.9% + 25¢ online. The monthly cost varies, so there is no single published plan to quote. Deposits can reach a Chase business checking account as soon as the same day at no extra cost. That is the cash-flow feature fintechs often price as a percentage.
Get a written quote. “Varies” can hide a PCI fee or a minimum. The quote is only useful next to your current effective rate.
What changes the bill after you sign
A chip or tap is cheaper than a card number typed into an invoice. Keyed-entry surcharges exist because those payments are easier to dispute.
A chargeback is not only a reversed sale. You pay a dispute fee and spend time gathering receipts. If your average ticket is small, a few disputes can erase the savings from a slightly lower rate.
“No monthly fee” can still include a PCI or non-compliance charge. Hardware that only pairs with one processor is a switching cost, even when the reader itself was cheap. Add that cost before you move for a 0.2 point difference.
Which service to pick
If you sell mostly in person and want cards working this week, start with Square. If you sell mostly online and may add subscriptions, start with Stripe. If customers ask for PayPal or Venmo, add that button even when another processor runs the cards.
If card volume is already past about $8,000 to $10,000 a month and the flat rate stings, price Helcim or a bank interchange-style offer against your effective rate. If the operating account is already at Chase and same-day deposit matters, get that quote before you pay a percentage for instant payout.
Pull last month’s processing fees and divide by card sales. Switch only if the new all-in rate beats that number after hardware, contract terms, and the time it takes to move.