Splitting bills fairly does not always mean splitting every cost down the middle. It means agreeing on what counts as shared, choosing a method that fits your incomes and responsibilities, and giving each person room to spend personal money without being questioned about every purchase.
A useful system has three parts: shared bills, shared goals, and personal spending money. Here’s how to set it up, handle tricky expenses, and check that it still feels fair as your lives change.
Choose a bill-splitting method that fits your household
There is no single right way to divide expenses. Start by comparing your incomes, responsibilities, and preferences. Then pick a method you can both explain and review.
Option 1: Split shared bills 50/50
With a 50/50 split, each person pays half of the agreed shared costs. This can work well when your incomes are similar and you have similar financial obligations.
The drawback is that equal dollar amounts can take up very different shares of each person’s income. If one partner earns much less, paying half may leave them with little room for savings or personal spending. A 50/50 split may also feel unfair if one person takes on more unpaid childcare or household work.
Option 2: Split bills in proportion to income
With a proportional split, each person contributes based on their share of the household’s combined take-home income.
For example, if one partner brings home $4,000 a month and the other brings home $6,000, their combined take-home pay is $10,000. The first partner earns 40% of that total, and the second earns 60%. For $3,000 in shared monthly costs, they could contribute $1,200 and $1,800.
This method can make shared costs more manageable when incomes differ. It also needs a shared definition of income. Many couples use take-home pay because that is the money available after payroll deductions. If one person has irregular income, you might agree on a cautious monthly estimate and revisit it when actual income is clear.
Option 3: Use a yours, mine, and ours system
A hybrid system keeps personal accounts for individual spending and uses a shared account, or another clear method, for joint bills and goals. Each partner contributes an agreed amount to the shared expenses, while the rest stays in their personal accounts.
You can base contributions on a 50/50 split, income shares, or another arrangement that feels workable. A hybrid can offer shared responsibility without requiring you to combine every dollar. Before opening a joint account, check the account terms and understand who can withdraw money or close it. Joint account rules can give each account holder broad access, depending on the account and applicable law. (consumerfinance.gov)
Decide what counts as a shared expense
A bill-splitting plan works better when both people know which costs are included. Write down the shared expenses instead of relying on memory or assumptions.
Common shared costs may include:
- Rent or mortgage, utilities, internet, and household insurance
- Groceries and shared household supplies
- Childcare, school costs, and children’s basic needs
- Shared transportation or pet expenses
- Savings for agreed household goals, such as a move or home repairs
Then decide what stays personal. That might include individual hobbies, clothes, lunches at work, personal subscriptions, gifts, or debt payments from before the relationship. Couples differ on what they consider shared, so the important part is to agree before bills are due.
Groceries and household shopping
Groceries can be a source of friction when one person buys mostly shared food and the other adds expensive personal items. Try setting a shared grocery budget for meals and household basics. Each person can buy special snacks, supplements, or personal items with their own spending money.
If your shopping habits differ, use separate receipts, a shared list, or a store account for household purchases. The aim is to make the boundary clear, not to audit each other’s food choices.
Childcare and uneven household work
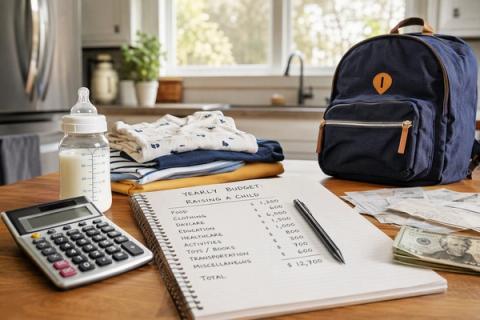
Treat childcare as a household cost if you both agree it supports your family. That includes regular daycare, after-school care, and agreed school expenses. For irregular costs, such as field trips, seasonal clothing, or medical copays, create a monthly category or savings pot instead of deciding who owes what each time.
Paid childcare is only one part of family work. If one partner reduces paid hours or takes on more childcare and household responsibilities, discuss whether a strict income-based contribution still feels fair. The goal is not to assign a price to every task. It is to recognize how paid work and unpaid work shape each person’s time and financial flexibility.
Set up the system in five steps
1. List your income and shared expenses
Write down each person’s usual take-home income, then list shared bills and typical monthly spending. Review several months of statements where possible, so less frequent costs do not disappear from the plan. Budgeting guidance from the Consumer Financial Protection Bureau recommends accounting for expenses that do not happen every month, such as medical costs, seasonal purchases, and gifts. (consumerfinance.gov)
Include subscriptions, annual fees, school costs, and bills that change during the year. A short review of bank and card statements can help you spot expenses you may have forgotten.
2. Agree on how to divide the shared costs
Choose 50/50, proportional contributions, or a hybrid. If you use a custom arrangement, write down the formula. For example, you might split housing costs based on income but share groceries evenly.
Make sure the arrangement leaves both people with enough money for personal needs and individual goals. If it does not, adjust the method or review which expenses you have labeled as shared.
3. Decide how to pay bills
You can pay from a shared account, assign specific bills to each person, or transfer agreed amounts to one person’s account. Choose the option that is easiest to track and least likely to cause missed payments.
If you use a joint account, understand its access rules and keep enough money there for upcoming bills. If you prefer separate accounts, use a shared bill tracker or calendar so both partners can see due dates and payment status.
4. Set shared goals and personal spending money
After covering bills, agree on shared savings goals. These might include an emergency fundCash set aside in an accessible account to cover unexpected expenses or a loss of income without taking on debt., a vacation, or a future home repair. Choose a monthly contribution that fits your budget and review it when your circumstances change.
Also agree that each person gets personal spending money that does not require approval from the other. The amounts do not have to be identical, especially if incomes differ. What matters is that both partners have some room to make everyday choices without feeling monitored.
5. Write down the agreement
Keep a simple shared note with your method, bill list, contribution amounts, payment dates, and savings goals. Include how you will handle one-off costs and what to do if income changes.
This does not need to be a legal document. It is a reference point that helps prevent the same disagreement from returning because each person remembers the plan differently.
Make irregular expenses part of the plan
A budget can look fair on paper and still cause conflict when surprise costs keep appearing. Some expenses are predictable but do not arrive monthly. Others, such as a car repair or an unexpected school cost, are harder to predict.
Create shared categories for costs such as:
- Annual insurance premiums and memberships
- Car maintenance and home repairs
- Children’s clothing, activities, and school expenses
- Gifts, travel, and seasonal events
- Medical and dental costs not covered by insurance
Estimate an annual amount for each category, then divide it by 12 to set a monthly target. If you do not know the cost yet, start with a reasonable estimate and adjust it after a few months. Keeping these costs visible can help avoid repeatedly treating them as emergencies.
Hidden subscriptions deserve a quick check, too. Review bank and card statements together once or twice a year. Cancel services you no longer use, and decide whether any remaining subscriptions are shared or personal.
Use a monthly money check-in
Schedule a 20- to 30-minute conversation once a month. Keep it focused on how the system is working, not on criticizing individual purchases.
Use this agenda:
- Check the numbers. Did shared bills and contributions match the plan?
- Look ahead. Are any large, annual, or child-related costs coming up?
- Review shared goals. Are you both comfortable with the savings amount and timeline?
- Raise one concern each. What felt fair this month? What felt stressful?
- Agree on any change. Name the change, who will handle it, and when you will review it.
A budget is a working plan, not a test of whether either partner behaved perfectly. The CFPB also recommends updating a budget when income or spending changes. (consumerfinance.gov)
Revisit the split when life changes
Review your arrangement after a job change, a new child, a move, a major change in childcare, or a shift in working hours. You can also review it if one person’s debt or family responsibilities begin to affect what they can contribute.
Try to talk before a change becomes a crisis. For example, if one partner expects a period of lower income, agree on a temporary contribution and a date to revisit it. A clear review date can keep a short-term adjustment from turning into an unspoken permanent rule.
Common bill-splitting mistakes to avoid
- Assuming equal means fair. A 50/50 split may not fit a household with very different incomes or caregiving responsibilities.
- Leaving costs undefined. Agree on whether groceries, childcare, pets, and subscriptions are shared.
- Forgetting irregular expenses. Include annual bills and predictable kid costs in the plan.
- Tracking personal purchases too closely. Once personal spending money is agreed, avoid requiring approval for ordinary purchases.
- Changing the rules without discussion. If the split no longer works, bring it up and agree on a new plan together.
- Combining accounts without understanding access. Review account terms before adding another person to an account. Joint account holders may have significant access to the funds, so make the decision deliberately. (consumerfinance.gov)
The fairest system is one you can revisit
A practical bill-splitting system does not need to be perfectly equal in every category. It needs to be clear, manageable, and flexible enough to reflect both partners’ contributions and changing circumstances.
Start with a method you can both explain. Define shared costs, protect room for personal spending, and set a regular time to review the plan. That gives you a better chance of solving money disagreements together instead of turning every purchase into a scorecard.