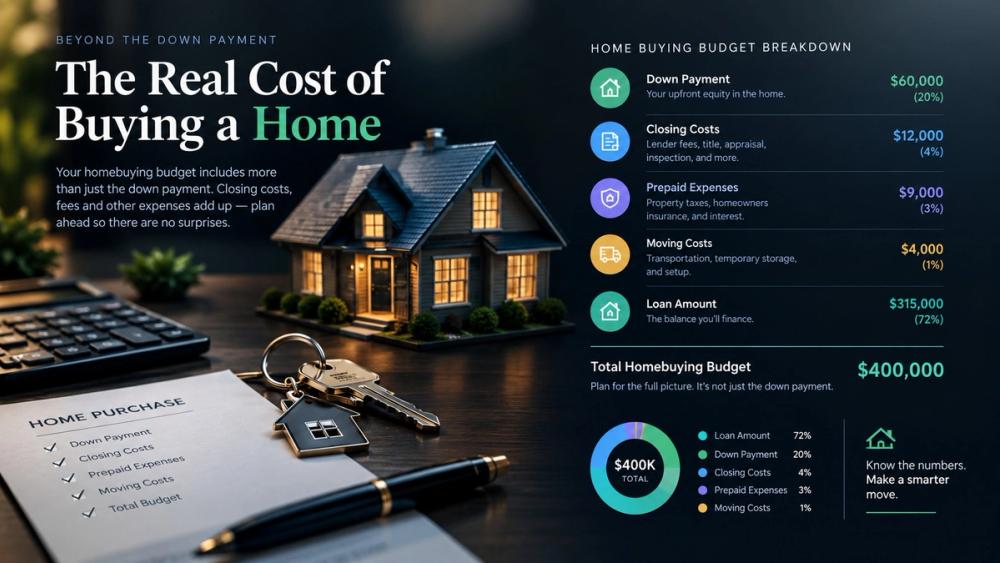
Closing costsThe fees and prepaid items due when a property sale or refinance completes — typically 2% to 5% of the loan amount for a buyer. are fees and prepaid expenses tied to finalizing a mortgage and transferring ownership. They are separate from your down payment, and they can include lender charges, third-party services, government fees, and items paid in advance, such as property taxes or homeowners insurance. Fannie Mae's closing-cost calculator notes that costs often range from 2% to 5% of the mortgage amount. Treat that as a starting estimate, not a quote: your loan, location, timing, and contract can change the total.
For a first-time buyer, the useful question is not only “How much are closing costs?” It is “How much cash will I need, and when will each amount be due?”
What closing costs can include
The exact line items vary. The Consumer Financial Protection Bureau's fee overview lists common charges such as appraisal fees, title insurance, government taxes, and prepaid expenses. Your Loan Estimate and Closing Disclosure show the charges for your specific mortgage.
| Cost group | Examples | What to check |
| Lender charges | Origination, underwritingThe process a lender or insurer uses to verify your finances and decide whether to approve you, and on what terms., application, or processing fees | Ask which fees are required and whether any can change before closing |
| Third-party services | Appraisal, title search, title insurance, settlement or attorney services | Confirm who selects the provider and whether you can shop for it |
| Government and recording charges | Recording fees and transfer or mortgage taxes, where applicable | Amounts depend on the state, county, and city |
| Prepaid and escrowMoney held by a neutral third party — either during a home purchase, or by your lender to pay property taxes and insurance. items | Prepaid interest, homeowners insurance, property taxes, and initial escrow deposits | These depend on your closing date, coverage, tax schedule, and escrow setup |
A prepaid amount is not always a fee for a service. Some money is collected in advance to cover bills that will come due after you own the home. Ask the lender to explain each line rather than treating every item as negotiable or optional.
Estimate a range, then replace it with your own numbers
If your mortgage amount were $250,000, a rough 2% to 5% planning range would be $5,000 to $12,500. That is an illustration of the range cited by Fannie Mae, not a prediction for a particular buyer. It does not include your down payment, and the final amount could fall outside the range.
Use a calculator for an early estimate, then use the lender's Loan Estimate to refine it. The CFPB says you should receive a Closing Disclosure at least three business days before closing. Use that time to compare the final figures with your Loan Estimate, ask about differences, and confirm the amount and payment method for closing. See the CFPB's guide to reviewing your Closing Disclosure.
Map the cash needs by stage
Before you make an offer
Set aside money for costs that may come due before the mortgage closes, such as a home inspection or appraisal. Ask the service provider when payment is due and whether a charge is refundable. These early costs may not appear in the final cash-to-close figure in the same way as closing-day charges.
After your offer is accepted
Review the purchase contract for any deposit requirements and deadlines. Ask your agent or closing professional how deposits will be handled and whether they will be credited toward the amount you owe at closing. Keep a record of what you paid and get written confirmation of how it appears in the final figures.
As your mortgage moves toward closing
Review your Loan Estimate and ask the lender to explain each fee, prepaid amount, and escrow deposit. If you are comparing lenders, compare the same loan amount, term, rate structure, and services. A lower fee in one category does not automatically mean the full offer costs less.
In the final days before closing
Check your Closing Disclosure when it arrives. Compare it with the Loan Estimate, verify credits and deposits, confirm your final cash-to-close amount, and follow the closing agent's verified instructions for payment. Contact the lender or closing professional promptly if anything is unclear.
Keep cash to close separate from the cost of owning the home
Your immediate cash need can include more than closing costs. A useful planning worksheet is:
Down payment + buyer closing costs + prepaid and escrow amounts + other due-before-close costs − deposits or credits applied = estimated cash to close.
Moving expenses, utility setup, furniture, maintenance, and urgent repairs are separate from mortgage closing costs. Keep a separate reserve for those costs if possible, rather than spending every available dollar to complete the purchase.
A down-payment assistance program may help with the down payment or, depending on its rules, other purchase costs. Check eligibility, repayment terms, and whether the program can be combined with your mortgage. Informer Money's guide to first-time homebuyer down-payment help explains grants, second liens, and low-down-payment loan programs. Assistance does not automatically eliminate closing costs or other cash needs.
Questions to ask before closing
- Which charges are lender fees, third-party services, government charges, or prepaid expenses?
- Which services can I shop for, and what is the deadline to choose a provider?
- Which charges may change between the Loan Estimate and Closing Disclosure, and why?
- How are my deposits, seller credits, or lender credits reflected in cash to close?
- What is due before closing, and what is due at the closing appointment?
- How should I verify the final payment instructions?
Your Loan Estimate and Closing Disclosure are the most relevant documents for your transaction. Use estimates for planning, confirm details with your lender and closing professional, and do not treat a general range as a guaranteed cost.