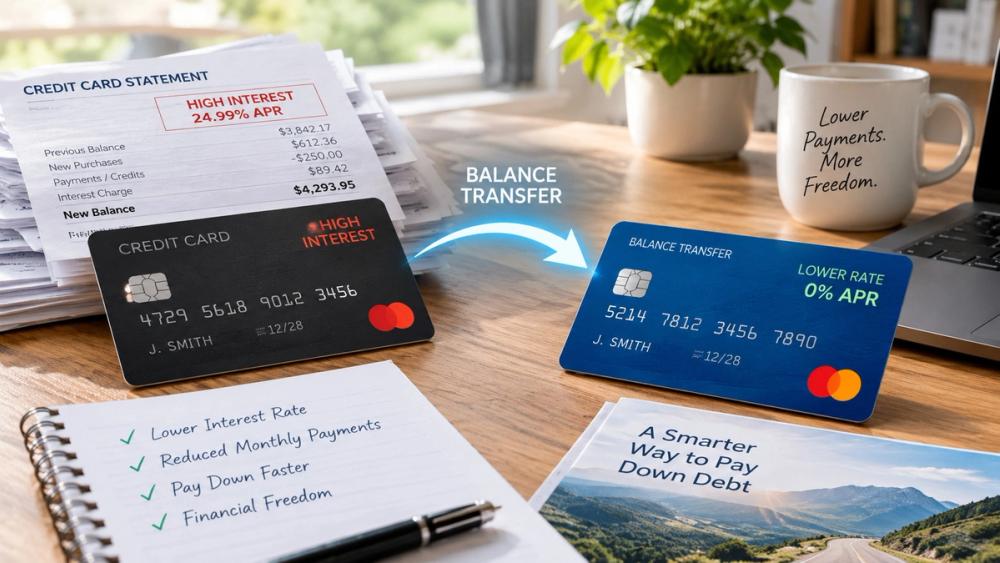
High credit card interest can make consistent payments feel unproductive. A balance transferMoving credit card debt onto a new card with a promotional low or 0% rate, so payments attack the balance instead of the interest. can reduce that burden by moving eligible debt onto a card offering an introductory interest rateThe percentage charged for borrowing money or paid for depositing it, quoted as an annual figure..
The best balance transfer cards after high-APRThe yearly cost of borrowing, expressed as a percentage that includes the interest rate plus most lender fees. credit card debt provide enough repayment time at an affordable total cost. However, transferring a balance doesn’t erase it. You still need a payment schedule that clears the debt before standard interest charges begin.
These eight U.S. cards serve different repayment needs. Compare current application disclosures before choosing because promotional offers can vary by application channel.
How to compare balance transfer cards after high-APR debt
Prioritize four factors: introductory APR, promotional duration, transfer fees, and the ongoing APR. A longer promotion may help your budget but a lower transfer fee could deliver greater savings.
Also distinguish the transfer deadline from the repayment period. An offer might require transferring debt shortly after opening the account while providing considerably longer to repay it.
Approval presents another hurdle. Balance transfer cards generally require good to excellent credit. Even approval may not provide enough credit to move your entire balance.
Treat rewards as secondary. Your immediate objective is reducing debt costs.
8 best balance transfer cards for high-APR credit card debt
1. Citi Diamond Preferred Card: For an extended balance transfer offer
Citi Diamond Preferred advertises 0% introductory APR on balance transfers for 21 months. Qualifying transfers must occur within four months of account opening. Its purchase promotion lasts 12 months, creating a different timeline for purchase balances.
This card deserves consideration when a shorter repayment window would strain your budget. Check the current transfer fee before applying. Avoid mixing everyday spending with transferred debt because the shorter purchase promotion adds complexity.
2. BankAmericard credit card: For a 21-billing-cycle repayment plan
BankAmericard advertises 0% introductory APR for 21 billing cycles on transfers made within the first 60 days. It also prohibits transfers that pay accounts provided by Bank of America.
That issuer restriction matters more than an attractive headline rate. If your existing debt qualifies, build your repayment schedule around the actual promotional expiration date. Preserve the distinction between billing cycles and calendar months when comparing offers.
3. Wells Fargo Reflect Card: For prioritizing repayment time
Wells Fargo Reflect appears among NerdWallet’s selections for the longest introductory periods on transfers and purchases. That positioning makes it worth comparing when monthly affordability drives your decision.
Start with the live transfer terms rather than secondary benefits. Confirm the introductory duration, transfer deadline, and applicable fee. Additional repayment time helps only when the resulting monthly target fits your budget and prevents a substantial balance from surviving the promotion.
4. U.S. Bank Shield Visa Card: For comparing a long promotion with added benefits
U.S. Bank Shield Visa also appears among long-introductory-period balance transfer options. NerdWallet identifies secondary benefits alongside its transfer positioning.
Evaluate those benefits after calculating repayment costs. A perk should not distract from a transfer fee that materially increases your balance. Compare Shield’s current disclosures against other suitable offers and confirm how much existing debt your approved credit limit can accommodate.
5. Chase Slate: For a debt-focused introductory-APR option
Chase Slate appears among cards offering long introductory periods for transfers and purchases. Forbes also identifies potential account reviews for higher credit lines as a distinguishing feature.
Consider that review feature incidental rather than part of your repayment strategy. A possible future increase does not guarantee additional transfer capacity. Choose Slate only if its initial approved limit, current transfer fee, and promotional timeline already support your plan.
6. Citi Simplicity Card: For no late fees or penalty rates
Citi Simplicity distinguishes itself through no late fees or penalty rates. Citi also markets introductory pricing on purchases and balance transfers, although readers must check the application-specific terms.
Those protections can reduce certain costs but they do not cancel required payments. Compare Simplicity directly with Diamond Preferred using current fees and promotional durations. Select the offer that supports repayment rather than assuming similarly branded cards provide identical terms.
7. Citi Double Cash Card: For usefulness after debt repayment
Citi Double Cash combines a balance transfer promotion with purchase rewards: 1% when buying and another 1% when paying. Citi warns that purchases can incur interest while you carry a transferred balance unless you pay the entire balance monthly.
Its strongest role may therefore come after debt repayment. Don’t confuse purchase rewards with savings on transferred debt. Keep new spending separate while evaluating the transfer offer.
8. Citi Strata Card: For a shorter promotion with future rewards
Citi Strata advertises 0% introductory APR for 15 months on purchases and balance transfers. It also offers rewards across several spending categories.
A shorter promotion requires faster repayment than a longer offer covering the same balance and fee. Consider Strata when your budget supports that pace. Its rewards may provide later usefulness but spending to earn them can undermine your immediate debt-reduction objective.
Calculate your balance transfer repayment target
Consider a hypothetical $6,000 transfer with a 3% fee. The fee adds $180, producing a $6,180 repayment balance.
At 0% APR across 18 equal monthly payments, you would need approximately $343.34 monthly. This example assumes no additional charges and a full 18-payment runway.
Use this sequence:
Existing debt → transfer fee → repayment balance → monthly target → promotional deadline
Compare the fee against projected interest without the transfer. Then build a repayment buffer rather than relying on the final promotional payment date.
Avoid mistakes that undermine balance transfer savings
Verify issuer restrictions before applying. Continue paying the original account until you confirm the completed transfer.
Set minimum-payment autopay as a safeguard and schedule additional payments toward your calculated target. Avoid new purchases unless you fully understand their separate interest treatment.
If your budget cannot support repayment before the promotion ends, reconsider the strategy. Ask your creditor about hardship assistance or explore nonprofit credit counseling instead of assuming another transfer will solve the remaining balance.
Choose the best balance transfer card for your timeline
Start with eligibility and monthly affordability. Then compare transfer fees, promotional duration, and the rate that follows.
The strongest choice gives you a realistic path to clearing debt without encouraging additional spending. Shortlist two suitable cards, review their current disclosures, and calculate your payment target before submitting an application.