Something expensive just happened. A dented bumper. A flooded basement. A bag stolen off a restaurant chair. You are already dealing with the mess. Now you also have to file an insurance claim.
This is where people lose money. Not because the policy is worthless. Because the process pays what the file can prove. Weak records produce weak checks.
The work follows a clear order. Read the policy. Document the loss. Report it fast. Stay factual until the file closes.
Why It's Important to File an Insurance Claim Correctly
Insurance is a contract. The company pays what the policy says it will pay if you meet the conditions. It does not pay based on how hard the week has been.
Most delays start early. People skip the policy. They wait too long to report. They take four photos instead of forty. A strong claim looks boring on purpose: dates, photos, receipts, and facts.
Step 1: Review Your Policy Before You File a Claim
Open the declarations page and the exclusions. Note the deductible, the coverage limits, and any deadline for reporting the loss.
Look for how soon you must notify the insurer. Check what the policy covers and what it leaves out. Confirm whether you have replacement cost or actual cash value coverage.
If a $1,000 deductible sits on a $1,200 repair, you may want to pay it yourself. A claim can still affect future premiums even when the payout is small. The Insurance Information Institute advises policyholders to understand coverage before the claim begins.
Step 2: Document the Incident Immediately
Record the damage while it is still visible. Once items get tossed or walls get patched, the story gets harder to prove.
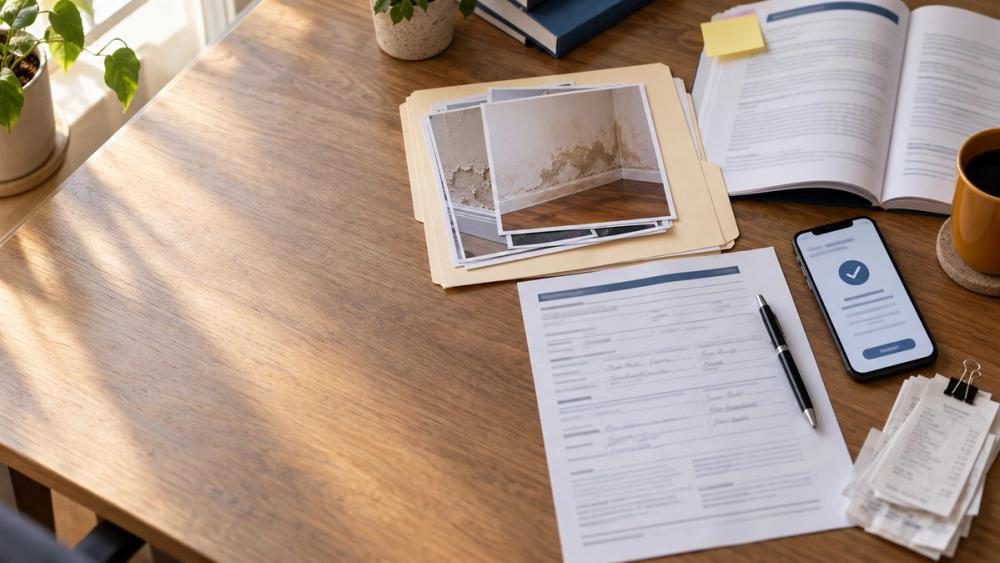
Take dated photos and video from several angles. Write down what happened with dates, times, and names. Keep receipts for emergency repairs and any police or incident report.
Don't throw damaged items out until the insurer says you can. Old receipts, serial numbers, and photos of the item in your home all help prove ownership.
Step 3: Contact Your Insurer Promptly
Call the claims line or file in the app as soon as it is safe. Many policies require prompt notice. Waiting weeks can give the company a reason to dispute the loss.
Have your policy number ready. Ask for the claim number and the name of the person handling your file. Find out what they need next and whether an adjuster will inspect the damage. Write those answers down.
Step 4: Complete the Claim Form and Submit Evidence
Fill every section of the form. Incomplete paperwork is a common reason claims stall.
Use facts. "Water entered through the north wall at 2 a.m. on June 3" helps. "This has been a nightmare" does not. Match dates and dollar amounts to the records you already have.
Send supporting documents in a clear order: police reports, repair estimates, medical bills, and proof of ownership. Send copies unless the company asks for originals.
Step 5: Work With the Insurance Adjuster
An adjuster reviews the loss and decides what the policy covers. Be there for the inspection if you can. Point out damage that is easy to miss.
Ask the adjuster to explain any exclusion they apply. Request reports and offers in writing. Keep notes from every call with the date and the person's name.
You don't have to take the first number. If the estimate looks low, get a second repair quote. For a large or complicated loss, some people hire a public adjuster. That person works for you rather than the insurer.
Step 6: Follow Up Until the Claim Closes
Claims slow down when nobody is watching. Put follow-up dates on your calendar. If a promised update does not arrive, send a short note with the claim number.
Keep one folder for everything: photos, forms, estimates, and settlement letters. If the claim is denied or underpaid, that file helps you appeal. It also helps if you contact your state insurance department.
Common Mistakes When Filing an Insurance Claim
Waiting too long to report is the first one. Taking too few photos is next. Making permanent repairs before the inspection can also hurt you. So can giving a recorded statement before you have the facts straight.
Do not accept the first offer without checking the math. DepreciationThe decline in an asset's value over time from age and use — and, for businesses, the tax deduction that tracks it. and the deductible will reduce the check. Home claims with replacement cost coverage often arrive in two payments. The first subtracts depreciation. The second comes after you finish the repairs.
If the repair is close to your deductible, consider using emergency savings instead. You avoid putting a claim on your record.
What to Expect After You File an Insurance Claim
A simple auto or renters claim can close in a few weeks. Complex home damage or injury claims take longer. After a storm, the queue gets longer still.
The usual sequence is report, investigation, inspection, offer, then payment. Ask for a timeline in writing. Then you will know when silence is a delay and when it is just the process.
Filing an insurance claim is not a fight you win with emotion. It is a record you win with order. If a number does not add up, ask for the calculation in writing before you cash the check.