Two investors turn 60 this year. One plans to start drawing from retirement savings next month. The other expects to work several more years and keep contributing. A market drop could affect both portfolios. For the first investor, it could also mean selling shares at lower prices to pay the bills. Asset allocationHow you divide a portfolio among stocks, bonds, cash, and other asset types — the single biggest driver of its risk and return. by age gives both investors a starting point for weighing how much to hold in stocks, bonds and cash as withdrawals approach.
What Should Drive Your Asset Allocation?
Asset allocation is how you divide a portfolio among stocks, bonds and cash. Stocks offer long-term growth potential and can swing sharply in the short run. Bonds can provide income and usually fluctuate less than stocks, although they can lose value. Cash keeps money available for spending but loses purchasing power when prices rise.
Start with when the money will be needed. That’s the investment’s time horizon. Risk tolerance is how willing an investor is to sit through a decline. Risk capacity is how much of a loss the investor can absorb and still cover expenses. Someone comfortable with market swings may have little room for losses if a large payment is due soon.
Asset Allocation by Age From Your 20s to Your 60s
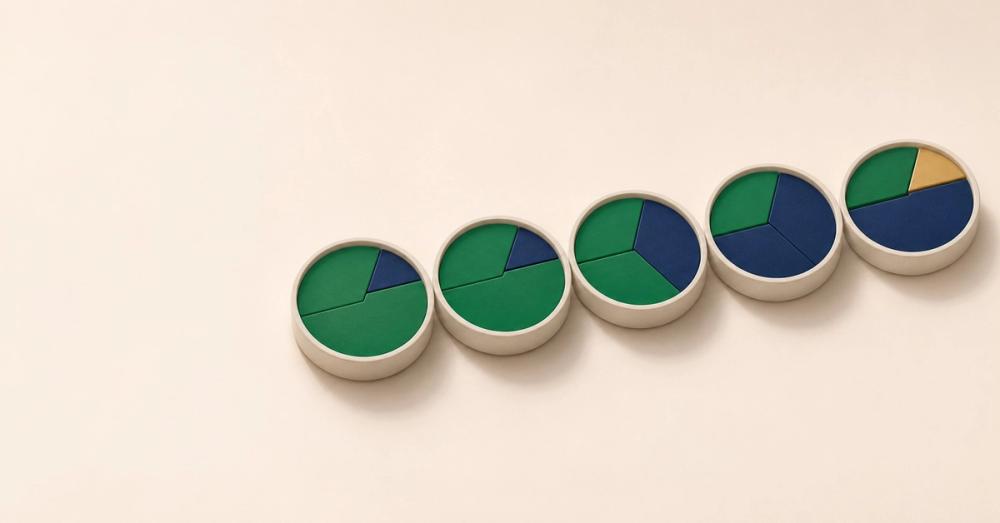
These five retirement portfolios use percentages within T. Rowe Price’s published ranges. The model assumes retirement at age 65 followed by 30 years of withdrawals. The examples show how a portfolio might change under those assumptions.
Asset Allocation in Your 20s — Build for Long-Term Growth
Example mix — 90% stocks and 10% bonds. With decades before retirement withdrawals, a saver has more time to ride out stock market declines. Spreading the stock allocation across companies and industries limits how much any one holding can hurt the portfolio.
Asset Allocation in Your 30s — Separate Retirement From Near-Term Goals
Example mix — 90% stocks and 10% bonds. The retirement timeline can still support the same stock allocation. A home down payment due in three years has a different deadline. Holding the down payment in cash can reduce the chance that a stock market decline delays the purchase.
Asset Allocation in Your 40s — Review Risk Across Accounts
Example mix — 80% stocks and 20% bonds. Add up stock and bond holdings across retirement accounts before judging the mix. A 401(k)An employer-sponsored retirement account that lets you invest part of your paycheck before taxes, often with a matching contribution. with employer shares and an IRA with a fund that owns those same shares can concentrate more money in one company than either account suggests.
Asset Allocation in Your 50s — Plan Around the First Withdrawal
Example mix — 70% stocks and 30% bonds. Retiring at 58 gives a saver nine fewer years to prepare than retiring at 67. Compare when paychecks stop, when other income begins and how much spending the portfolio must cover. Those dates help determine how much money needs to be available for early withdrawals.
Asset Allocation in Your 60s — Balance Withdrawals and Future Growth
Example mix — 55% stocks, 40% bonds and 5% cash. Subtract expected Social Security and pension income from planned spending to estimate what the portfolio must cover. Selling shares during an early downturn leaves fewer shares to benefit from a recovery. That’s sequence-of-returns riskThe risk that poor investment returns early in retirement permanently damage a portfolio, even if the long-run average is fine., or the risk that the timing of losses shortens how long savings last. Cash and short-term bonds can help cover upcoming expenses while stocks offer growth potential for later years.
How to Adjust and Rebalance Your Retirement Portfolio
RebalancingPeriodically buying and selling to return a portfolio to its target mix after market moves have shifted it. brings a portfolio back to its target after market moves change the mix. Suppose stocks rise and a 70% stock and 30% bond portfolio shifts to 75% stocks and 25% bonds. Directing new contributions toward bonds can move it back toward 70/30. Selling some stocks can close the gap sooner and may trigger capital gainsThe profit from selling an asset for more than you paid, taxed at a lower rate if you held it longer than a year. taxes in a taxable account.
Moving up retirement can justify changing the target itself because withdrawals will begin sooner. If a rally pushed the stock allocation higher and the retirement plan still holds, the existing target gives the investor a reference point. Informer Money covers how to set a rebalancing rule in 7 Portfolio Mistakes Investors Make.
Frequently Asked Questions
Does the “100 Minus Your Age” Rule Still Work?
The rule gives a 50% stock allocation at age 50. It offers a quick estimate and leaves out withdrawal timing, other retirement income and the investor’s ability to absorb losses.
Is a 60/40 Portfolio Appropriate at Age 60?
A mix of 60% stocks and 40% bonds can fit some retirement plans. Its suitability depends on the spending gap, the first withdrawal date and the investor’s ability to absorb losses.
How Often Should I Review My Asset Allocation?
An annual review gives investors a regular time to check their mix. A preset threshold, such as a five-percentage-point shift in the stock allocation, can also prompt a rebalance between reviews.
Can a Target-Date Fund Adjust My Asset Allocation Automatically?
A target-date fundA single fund that holds a whole diversified portfolio and shifts automatically from stocks toward bonds as its target year approaches. adjusts its investments on a schedule called a glide path. Funds with the same target year can hold different stock percentages at retirement, continue adjusting for different lengths of time and charge different fees.
Put Your Asset Allocation in Context
Use asset allocation by age to choose a starting point. Write down when withdrawals will begin and how much annual spending the portfolio must cover. Compare those needs with the current stock, bond and cash mix before deciding whether to change the target.