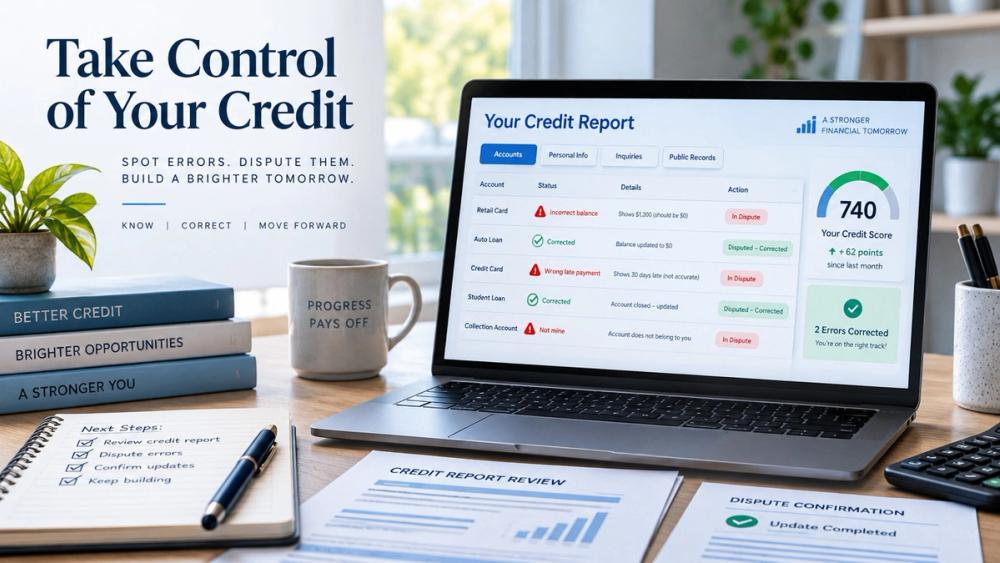
A wrong account, a payment marked late after you paid, or a debt that is not yours can raise the cost of a loan. It can also stall a rental application or complicate a job check. You have a legal right to dispute errors on your credit report. Success is not a quick phone call and a hope. It is a clear mistake, proof, and a written trail with the credit bureau and the company that reported the item.
What counts as a credit report error worth disputing
A credit report dispute works only when the information is wrong, incomplete, or not yours. Accurate late payments, real collections, and closed accounts you actually had will stay. Disputing true history wastes the review and can get the request treated as incomplete.
Errors that belong in a dispute include accounts you never opened, wrong balances or credit limits, and payments marked late after you paid on time. Closed accounts still shown as open, the same debt listed twice, and accounts mixed with another person's file also qualify. Most negative items should fall off after seven years. Most bankruptcies drop after seven or ten years, depending on the chapter. If an item is still there past that window, dispute it.
What a dispute will not fix is a true debt you dislike. You can add a short statement later if you disagree with a verified item. That statement explains your side. It does not delete the account.
Pull the reports before you dispute
Check all three nationwide bureaus before you file. An error on Equifax may be missing from Experian or TransUnion. You can get a free report from each bureau every week at AnnualCreditReport.com, the official site named by the Federal Trade Commission.
Save each report. Circle the bad item. Write down the furnisher, which is the bank, card issuer, landlord, or collector that supplied the data. Note the account number as it appears, the date opened, and the status you believe is wrong. One highlighted page is more useful than a vague complaint that "something looks off."
Build a file a reviewer can follow
The Consumer Financial Protection Bureau says a dispute should explain what is wrong, why, and include copies of supporting documents. Include your full name, current address, and phone number. Name the account, state the error in one or two sentences, and say what the record should say instead.
Send copies, never originals. Useful proof includes statements, payment confirmations, letters from the creditor, and identity documents if the account is not yours. For identity theft, an IdentityTheft.gov report strengthens the file. Attach a copy of the report page with the item circled.
Keep a simple log: date sent, method, and confirmation or tracking number. Certified mail with a return receipt is the cleanest paper trail. Online disputes are faster, but they are weaker if you later need to prove exactly what you sent. The CFPB offers a sample dispute letter you can adapt. Do not copy a generic "credit repair" template that disputes every negative line.
Dispute with the bureau and the company that reported it
Fixing an error generally means contacting both sides. File with each credit bureau that shows the mistake. A correction at one bureau does not automatically clean the other two.
You can dispute online, by phone, or by mail:
- Equifax accepts disputes through its online portal. Mail to the address on your report if you want a paper record.
- Experian takes disputes at experian.com/disputes. Mail goes to Experian, P.O. Box 4500, Allen, TX 75013.
- TransUnion takes disputes at dispute.transunion.com or by phone at (800) 916-8800.
The bureau generally has 30 days to investigate. That window can extend to 45 days if you send more documents after you file. It must forward your dispute and relevant proof to the furnisher, then report the results to you in writing. If the investigation changes your file, you also get a free updated report.
Send a separate letter to the furnisher. Use the dispute address on your credit report, not a general customer-service box. The CFPB's furnisher letter is a useful model. If the company cannot verify the item, it must tell the bureaus to update or delete it and notify every bureau it reported to. If it keeps reporting the item while your dispute is open, the bureau should note that you are disputing it.
A thin dispute can be rejected as frivolous or irrelevant. If you do not name the account or explain the error, the bureau can decline to investigate and must tell you why, generally within five business days. Rewrite with the account details and proof. Do not resend the same vague letter.
Read the result, then decide the next move
Three outcomes are common.
If the item is corrected or deleted, recheck all three reports within a few weeks. Confirm the furnisher stopped reporting the old version. A fix that appears on one file and not the others still needs a separate dispute.
If the bureau says the item was verified as accurate, you can ask that a brief statement of dispute be added to your file and future reports. Keep it factual and short. Lenders may read it. They are not required to ignore the underlying account.
If the error remains after a proper dispute, file a complaint with the CFPB. The law expects you to dispute with the credit reporting company first. For fraud, report the theft, place a fraud alert or credit freeze, and dispute the fraudulent accounts with both the bureau and the furnisher.
Mistakes that sink an otherwise valid dispute
Disputing every negative item at once makes a real error harder to see. Sending originals risks losing the only proof you have. Paying a company to send mass letters rarely beats a specific file you build yourself. Skipping the furnisher leaves the source of the error in place. Assuming one bureau speaks for the other two leaves the mistake on the reports a lender might actually pull.
A sequence that works
Get the three reports. Mark only real errors. Gather copies and write a plain explanation of each mistake. Dispute every bureau that lists the item, and dispute the company that furnished it. Track the 30-day clock. Read the written result, recheck the reports, and escalate only if the error remains.
A successful credit report dispute is specific, documented, and filed in two places. Accurate bad news stays. Inaccurate bad news does not have to.