A credit report is not a full picture of your money life. It is a focused record of how you have handled debt. The three major bureaus—Equifax, Experian and TransUnion—build these files from data lenders and courts send them. Knowing exactly what lands in the file and what stays out helps you catch errors and understand why a lender makes the decisions it does.
The Four Core Sections That Appear on Every Credit Report
Credit reports follow a predictable structure. Four main sections show up almost every time.
Personal Identifying Information
This section confirms the file belongs to you. It lists your full legal name plus any prior names or aliases you have used. Current and past addresses appear. So does your date of birth and usually a partially masked Social Security number. Phone numbers and employer names from past applications can show up too. These details exist only for matching. They do not feed into credit scoresA three-digit number, typically 300 to 850, that lenders use to estimate how likely you are to repay borrowed money..
Credit Accounts (Tradelines)
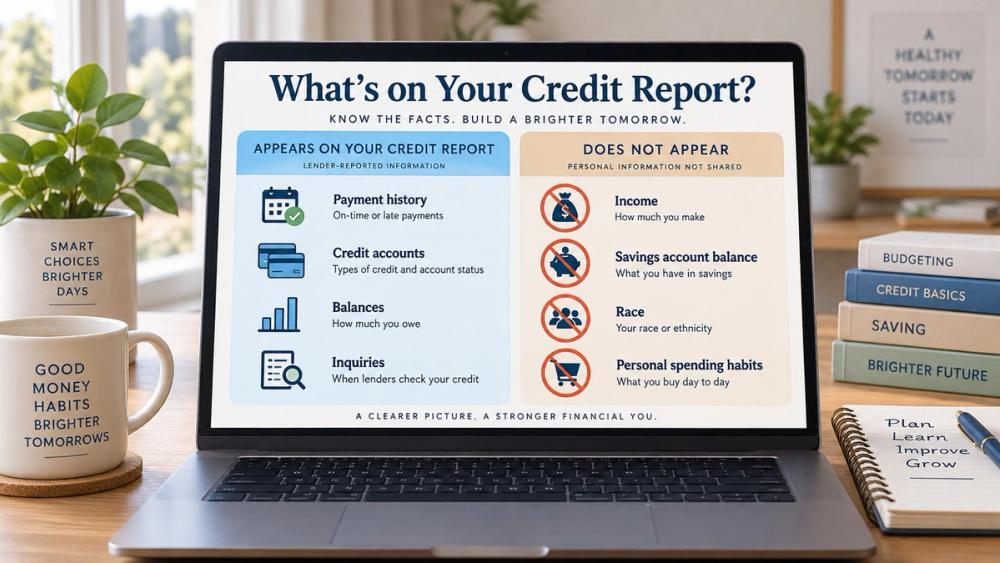
This is the heart of the report. Every credit card, auto loan, mortgage, student loan or other credit account the bureaus know about gets its own entry. You will see the creditor’s name, the account type, the open date, the credit limit or original loan amount and the current balance. A month-by-month payment grid shows whether you paid on time or fell 30, 60 or 90-plus days behind. Highest balance and current status—open, closed, charged-off or in collection—also appear. Individual purchases never show. Closed accounts that stayed in good standing usually remain for up to ten years after the last activity.
Credit Inquiries
Any time someone pulls your report the request gets logged. Hard inquiriesA lender's review of your credit report when you apply for credit — recorded on the report and worth a few points for about a year. happen when you apply for new credit. Soft inquiries cover your own checks, pre-approvedA lender's conditional commitment to a loan amount after reviewing your finances — stronger than a prequalification, short of an approval. offers and routine account reviews. Both stay on the report for up to two years. Only hard inquiries can nudge a score and the effect is usually short-lived. An inquiry appears only on the bureau or bureaus the lender actually checked.
Public Records and Collections
Bankruptcy is now the only public record the three national bureaus still report. Chapter 7 filings can stay up to ten years from the filing date. Chapter 13 filings usually drop after seven. Collection accounts appear as separate tradelines when an unpaid debt is sold or assigned to a third-party collector. They remain for seven years from the original delinquency date. Civil judgments and most tax liens were removed in 2017–2018 after the bureaus tightened data standards.
What Does Not Appear on a Credit Report
The exclusions matter just as much as the inclusions.
Income, Assets and Everyday Finances
Your salary, wages, bank balances, investment accounts, retirement savings and net worthEverything you own minus everything you owe — the single clearest measure of your overall financial position. never appear. Neither does your debt-to-income ratioThe share of your gross monthly income that goes to debt payments — a key test lenders apply when sizing a mortgage. or individual cash transactions. Lenders ask for income and asset proof during underwritingThe process a lender or insurer uses to verify your finances and decide whether to approve you, and on what terms.. They do not get that information from the credit bureaus.
Non-Credit Obligations and Personal Details
Rent, utilities, cell-phone bills and streaming services stay off the report unless they go to collections. Most medical bills follow the same rule. Marital status, race, religion, education level, criminal records and medical diagnoses are barred by law or industry practice. Your actual credit score is also missing. The score is calculated on demand from the data inside the file. It is never printed on the report itself.
How Long Information Stays and Why Timing Matters
Most negative items fall off after seven years measured from the date of first delinquency. Bankruptcy can stay longer. Hard inquiries disappear after two years. Positive closed accounts typically remain for up to ten years. Paid medical collections no longer appear under current industry agreements. As negative items age they carry less weight. Adding new on-time accounts speeds the recovery.
Practical Steps for General Readers
Pull your free reports once a year at AnnualCreditReport.com—the only site authorized by federal law. Check all three bureaus because not every creditor reports to every one. If you spot an error gather your documentation and dispute it with both the bureau and the company that supplied the data. Some people use tools such as Experian Boost to add on-time utility or rent payments. Those additions affect only that bureau’s file.
A credit report records debt behavior. It does not record how much you earn or what you own. Review the file, correct what does not belong and keep adding positive history. That is the clearest path to a stronger standing with lenders.